Accountant for doctors, physicians and medical professionals.
EK CPA provides accounting services for doctors across Ontario: family physicians, specialists, surgeons, locums and medical clinics. Elena Kanter, CPA, CA prepares your corporation's tax return and your own, reconciles OHIP and keeps the monthly books, for practices from Whitby and Oshawa to Scarborough and Toronto. Fixed fees, quoted before we start.
What a medical accountant actually does.
A physician's finances do not look like a typical small business. OHIP pays fee-for-service claims through a monthly remittance advice that rarely lines up with the month you did the work. Locum income can arrive as employment income, self-employed income or corporate income. Medico-legal reports can be taxable when your clinical work is not. And a Medicine Professional Corporation (MPC) needs a certificate of authorization from the CPSO, renewed every year, plus share rules set by provincial law.
A medical accountant keeps all of that straight and compliant: accounting and bookkeeping that ties OHIP and private billings to the bank, tax filing for the corporation and for you, staff pay and proactive tax planning before the big decisions, from incorporating to joining a group practice.
A psychiatrist, or a therapist or social worker in private practice? Your billing and HST questions are different, and each has its own page: see our accountant for psychiatrists and accountant for therapists pages.
Accounting and tax services for medical professionals.
One accounting firm for tax, bookkeeping and financial management. One point of contact and one consistent set of advice, so you can stay focused on patient care.
Corporate and personal tax returns
Your MPC's T2 and your personal T1, prepared together and filed on time, with salary, dividends and RRSP room planned before year-end.
OHIP and billing reconciliation
Each monthly remittance advice matched to your books, with private billings, uninsured services and third-party fees tracked separately so revenue is right at year-end.
Monthly books for practices and clinics
Every month we reconcile the bank and cards, split shared overhead with other doctors correctly and produce financial statements you can actually read.
Incorporation and tax strategies
Whether and when to incorporate, the CPSO certificate of authorization and how to pay yourself afterwards, modelled with your real numbers.
HST on third-party work
Medico-legal reports, insurance examinations and cosmetic work reviewed for HST, with registration handled when taxable billings pass the $30,000 small supplier threshold.
Staff pay and group practices
Payroll for nurses, receptionists and admin staff, with T4s and T4As at year-end. For group practices, cost-sharing and shareholder arrangements kept consistent across every physician.
Doctor tax traps that cost physicians money.
These come up almost every time a physician changes accountants. Worth knowing whether or not we end up working together.
Not every billing is HST-exempt.
OHIP-insured services and other care provided for a patient's health are exempt from HST. Since 2013, the test is the purpose of the service, not who pays for it: medico-legal reports, insurance examinations and other assessments made only for a legal or insurance decision are taxable, and so is cosmetic work that is not for medical or reconstructive reasons. Once those taxable billings pass $30,000 over four consecutive calendar quarters, you register and charge HST on that portion.
Locum income can be taxed three ways.
Locum work can be paid to you as an employee on a T4, as self-employed income, or to your MPC, depending on the arrangement with the host. Each path has different source deductions and different planning, and the wrong one can be expensive. We look at the actual contract and set it up so the treatment holds up if the CRA asks.
Income splitting is narrower than it looks.
Ontario lets an MPC issue non-voting shares to a physician's spouse, child or parent, or to a trust for minor children, while voting shares stay with physicians. But shares of a professional corporation can never be excluded shares under the tax on split income (TOSI) rules, so dividends to adult family members are taxed at the top rate unless another exception applies, such as your spouse once you turn 65.
Passive income shrinks your small business limit.
From 1 July 2026, an Ontario medical corporation pays 11.2% on the first $500,000 of active business income. Once the corporation and any associated companies earn more than $50,000 of passive investment income in a year, that limit drops by $5 for every $1 over, and it is gone at $150,000. For established doctors investing inside the MPC, it is one of the most common avoidable tax costs.
Medical professionals we work with.
Family physicians and clinic owners
Solo practitioners and group clinics. We handle both tax returns, OHIP reconciliation, staff pay and a quarterly check on cash flow.
Specialists and surgeons
Hospital-based or clinic-based, with OHIP billings, hospital pay and private or third-party fees. We keep the corporate tax planning consistent across all of it.
Residents, new physicians and locums
Earning across several sites for the first time. We sort out the tax treatment, set instalments so the first big year is not a surprise and advise on when to incorporate.
You work directly with Elena.
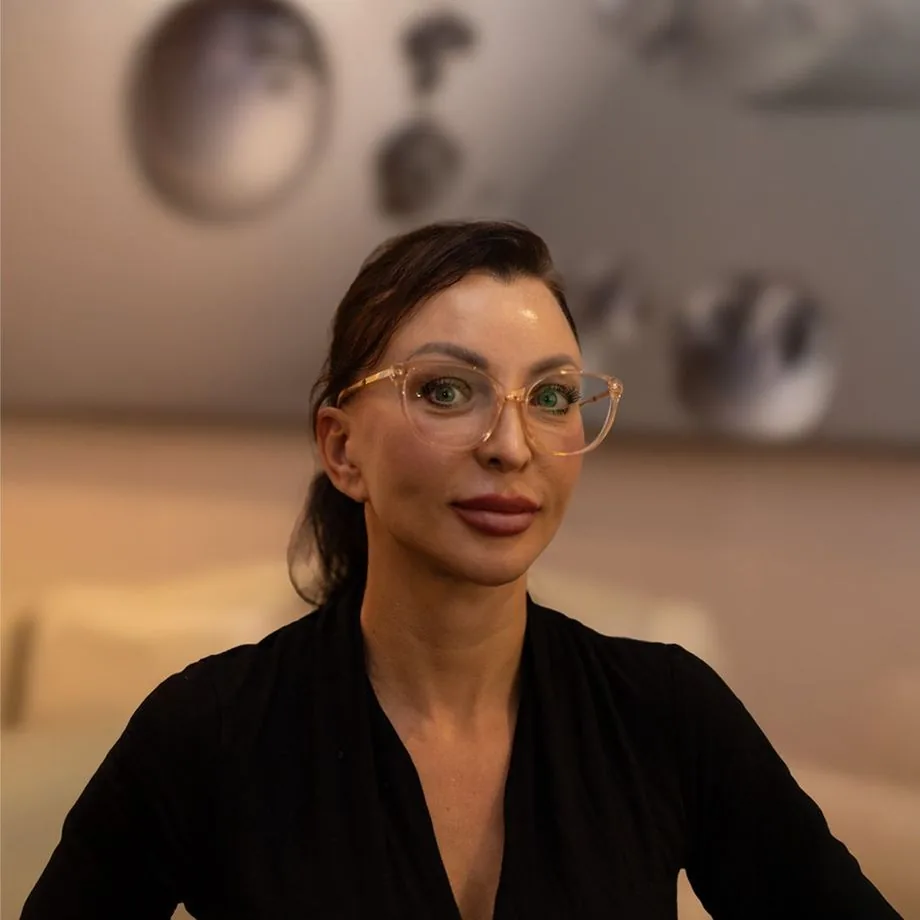
EK CPA Pro is owner-operated. Elena Kanter has been a CPA, CA (chartered professional accountant) since 2009, has worked in accounting firms from small Durham practices to large international organizations and is a graduate of CPA Canada's In-Depth Tax Program. Her client work spans medical, dental and chiropractic practices. When you call, you reach the CPA doing your file, not a junior who passes it along at year-end.
Questions doctors ask first.
What does an accountant for doctors cost?
A fixed fee, quoted before we start. The price depends on the size of the practice and its accounting needs: whether there is a corporation, how many transactions there are each month, how many people are on payroll and whether OHIP and private billings both need reconciling. You see the number up front, there is no hourly billing and the first 30-minute consultation is free.
What do accounting services for doctors include?
Usually four things: monthly books with OHIP and private billings reconciled to the bank; the MPC's T2 and your personal T1, planned together; staff pay and year-end slips; and advice on incorporation, your pay mix, HST on third-party work and investing inside the corporation. Some physicians only need the year-end and the returns. We quote whichever you need.
Should I incorporate my medical practice?
Usually, once your billings comfortably exceed what you spend personally. There is no fixed income threshold in law. Income left in an MPC is taxed at 11.2% on the first $500,000 from 1 July 2026, and the corporation needs a CPSO certificate of authorization before it can practise. The right answer depends on your debt, your spouse's income, what you are saving for and your retirement plans. We model both options with your real numbers first.
How does HST work for an Ontario doctor?
OHIP-insured services and care provided for a patient's health are exempt, so you do not charge HST and generally cannot claim input tax credits on the related costs. Taxable work is the exception: cosmetic procedures that are not for medical reasons, medico-legal reports and insurance examinations. Only that taxable revenue counts towards the $30,000 small supplier threshold over four consecutive calendar quarters. Cross it and you register and charge HST on the taxable portion only.
Can my spouse or children own shares of my medical corporation?
Non-voting shares, yes. Ontario allows a physician's spouse, child or parent, or a trust for minor children, to hold non-voting shares; voting shares stay with physicians. TOSI then usually taxes dividends to adult family members at the top rate unless an exception applies, such as your spouse once you turn 65. There are still planning opportunities, and we walk through the ones that fit your situation.
What can I deduct as a physician?
Most costs of running the practice: clinic rent or your overhead share, staff wages, medical supplies, CPSO and medical association dues, professional liability protection, continuing education and medical equipment. Instruments under $500 are Class 12 at 100%, most clinical equipment is Class 8 at 20% and computers are Class 50 at 55%. The grey areas are vehicle use, home office and conference travel. We go through the list in the first meeting.
Do you do bookkeeping for medical professionals, or just the year-end?
Both. Monthly bookkeeping for a physician or a clinic means each OHIP remittance advice and every third-party billing reconciled against what actually lands in the account, overhead shared correctly with other doctors and source deductions remitted on time. Billings often settle weeks after the service date, so without monthly reconciliation the revenue in your books rarely matches the practice.
Do you work with physicians outside Durham Region?
Yes. The office is in Whitby, and we work with doctors and medical clinics in Oshawa, Ajax, Pickering, Scarborough, Toronto and across the GTA. Most of the work runs online, so physicians elsewhere in Ontario work with us remotely, with meetings by video or in person when it helps.